UK ISAs · August 2026
How to transfer an ISA: start with the new provider (it is not a withdrawal)
Capital at risk. The value of investments can fall as well as rise, and you may get back less than you put in. Past performance is not a guide to future returns.
Some links on this page are referral links. If you use them, we may earn a commission at no extra cost to you. This never affects how we rate products. How we make money
FSCS protects eligible deposits up to £120,000 per person, per authorised institution.
Last updated: 27 September 2026.
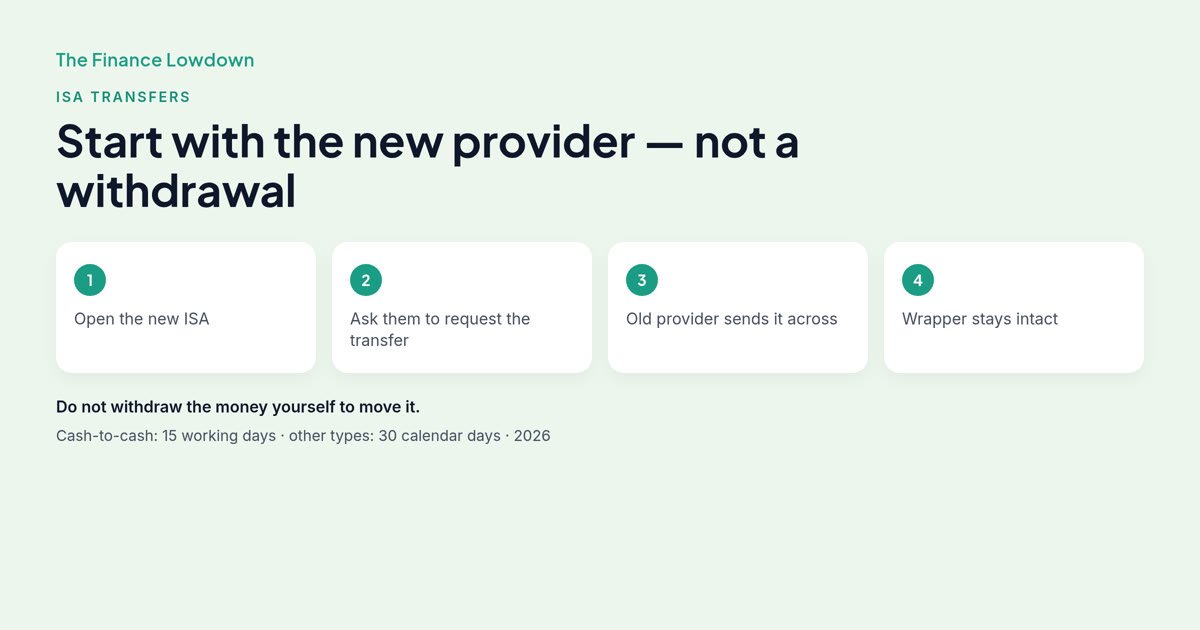
An ISA transfer is a manager-to-manager move of the tax-free wrapper. You start with the provider you want to move to. You do not close the old account and pay the money into a new one.
Never withdraw cash yourself when transferring an ISA — always use your new provider’s official ISA transfer service to preserve your tax-free status.
Cash-to-cash has a 15 working-day clock. Other types have a 30 calendar-day clock, not 30 working days. This is general information, not personal advice.
It is not a recommendation to transfer, and it is not investment advice.
Official process: GOV.UK transferring your ISA.
Quick answer
- Transfer through the new provider — do not withdraw and reopen if you want to keep ISA benefits.
- CASS does not move ISAs; ISA transfers are a separate process and often take up to about 30 calendar days.
- Check exit fees, in-specie vs cash transfer, and whether you will be out of the market during a cash transfer.
- The 2026/27 ISA allowance is £20,000; a transfer of previous years’ subscriptions does not normally reuse this year’s allowance.
Why a transfer is not a withdrawal
HMRC: they cannot transfer an ISA by closing it and paying the proceeds into a new ISA. Paying the investor is a withdrawal; the wrapper is lost.
GOV.UK consumer wording: you will not be able to reinvest that part of this year’s allowance. Previous-year capital, and Stocks and Shares gains, sit outside the shelter once withdrawn.
A flexible ISA’s replace-in-year right does not rescue a DIY move to a different provider. Flexibility is same account, same tax year, cash only.
Lifetime ISA and Junior ISA cannot be flexible. A transfer is listed among withdrawals that cannot be replaced without counting to the limit.
It is not a Current Account Switch Service switch. See current account switch bonuses.
How to transfer an ISA (numbered process)
GOV.UK: contact the ISA provider you want to move to and fill out an ISA transfer form. HMRC (27 March 2025): to start the transfer, the investor will approach the new ISA manager.
Managers must allow transfer-out. They are not obliged to accept transfer-in or partials.
- Check the receiving manager will take it. Transfer-out is a right. Transfer-in and partials are not. Check charges, notice or fixed penalties, in-specie versus cash, and whether they hold the lines.
- Start with the new provider. Contact the ISA provider you want to move to and fill out an ISA transfer form, plus an application if it is a new account. Typical fields: name, address, date of birth, National Insurance number, old account identifiers, full versus part, years, and any notice instruction.
- Do not withdraw and reopen. Do not close the old account and pay the proceeds into a new ISA. Managers move the wrapper direct. A DIY self-transfer voids the wrapper.
- Managers move it. The new manager sends a transfer instruction. For cash-to-cash that is five business days, then the old manager sends funds and a transfer history form in five business days, then the new manager applies in three business days. The history form is manager-to-manager, not for the customer.
- Current year versus previous years. From 6 April 2024 the law allows whole or part of both current-year and previous-year subscriptions. Many providers still require the current year in full. Lifetime ISA current year must go in full. Junior ISA same-type transfer is the entire account.
- Flexible ISA. Same-year cash replace only if that provider offers flexibility. A transfer is not a replaceable withdrawal. Lifetime ISA and Junior ISA cannot be flexible.
- In-specie or cash for Stocks and Shares. The investor chooses if both managers can do it. Fractionals are often sold inside the wrapper. Do not trade mid-transfer. You are out of the market only if holdings are sold. Capital can fall as well as rise.
- How long it takes. Cash-to-cash: 15 working days. Other types: 30 calendar days, not 30 working days. Platform in-specie tables can run longer. Notice or fixed-term waiting to avoid a penalty is a new instruction and a fresh clock.
- Lifetime ISA and type-change. Lifetime ISA to Lifetime ISA does not trigger the 25% charge; the bonus travels. Lifetime ISA to another type is treated as a withdrawal, with the 25% charge unless age 60, terminal illness, or a qualifying first home. Do not overlap with a conveyancer first-home withdrawal.
- If it overruns. Contact the ISA provider. Industry practice is that the new provider chases from day 10 (TISA, not GOV.UK). Then the Financial Ombudsman Service. Do not use the Current Account Switch Service.
- 2027 forward note, not in force. From 6 April 2027, for under-65s, a £12,000 Cash ISA subscription cap is announced and Stocks and Shares or Innovative Finance to Cash is blocked in draft rules. Cash to Stocks and Shares remains allowed. This is not in force on 30 August 2026 and is not advice to sell.
- FSCS, joint, and CASS pointers. A Cash ISA is a deposit, covered up to £120,000 per person per authorised firm. Stocks and Shares investment shortfall is still £85,000. You cannot hold an ISA with someone else. The Current Account Switch Service does not move ISAs.
Cash vs Stocks and Shares clocks
Clocks as of 30 August 2026 from the ISA Regulations and GOV.UK. Cash-to-cash is 15 working days. Other types are 30 calendar days, not 30 working days.
| Move | Clock | Note |
|---|---|---|
| Cash ISA to Cash ISA | 15 working days | From when the new manager receives the instruction. Industry aim: 85% in 7 working days. |
| Stocks and Shares, Lifetime ISA, cross-type, IFISA cash | 30 calendar days | Not 30 working days. Platform in-specie tables can run longer. |
| IFISA non-cash investments | Ask the provider | Not a GOV.UK 15- or 30-day figure on this snapshot. |
Notice or fixed-term: waiting to avoid a penalty is a new instruction and a fresh clock. Industry (not HMRC): old interest stops on the day funds leave; new provider backdates so there is not a dead gap. If it overruns, GOV.UK says contact your ISA provider, then the Financial Ombudsman Service.
In-specie versus cash
For Stocks and Shares, the investor chooses in-specie or cash if both managers can do it. Fractionals (Trading 212, Freetrade, Moneybox T&Cs) are sold; cash should stay in the ISA. A cash transfer is out of the market until rebuy. You can check a firm’s details on the FCA Register.
Capital can fall, or you can miss a rise. In-specie usually stays invested but often cannot deal until complete.
AJ Bell, Hargreaves Lansdown and interactive investor: choice on the form. Vanguard: own funds in-specie; non-Vanguard sold. Nutmeg: usually cash.
Do not trade mid-transfer. Unsupported lines are often sold. Residual cash after stock still moves inside the ISA.
See Stocks and Shares ISA fees for costs, not a destination pick.
Partial versus full
From 6 April 2024, current-year and previous-year subscriptions may be transferred in whole or in part. Law allows it; many T&Cs do not. Pay.UK Cash ISA Transfer Service list v7.0 (10 July 2026): most participants still No for partial current-year.
Lifetime ISA current year must go in full. Junior ISA same-type transfer is the entire account.
You cannot hold an ISA with someone else. See joint savings accounts.
Lifetime ISA special rules
Lifetime ISA to Lifetime ISA does not trigger the 25% charge. The bonus must travel. Current year in full.
Clock: 30 calendar days. Lifetime ISA to Cash, Stocks and Shares or Innovative Finance is treated as a withdrawal, with the 25% charge unless age 60, terminal illness, or a qualifying first home.
Do not run a Lifetime ISA transfer in parallel with a live first-home conveyancer withdrawal. A Lifetime ISA-to-Lifetime ISA transfer does not reset the 12-month first-home clock. Full rules: Lifetime ISA rules.
2027 forward note (not in force)
From 6 April 2027, a £12,000 Cash ISA subscription cap for people under 65 has been announced. Draft rules also block Stocks and Shares or Innovative Finance to Cash for under-65s. Cash to Stocks and Shares remains allowed.
From the tax year they turn 65, people keep £20,000 cash and transfers to Cash. The overall ISA allowance stays £20,000. Stocks and Shares is not capped.
These changes are draft / announced. They are not in force on 30 August 2026. This is not advice to sell.
Fees snapshot
Published transfer-out facts as of 30 August 2026. This is not a destination ranking and not a recommendation to transfer to anyone.
| Provider | Transfer-out |
|---|---|
| AJ Bell D2C ISA (from 10 Jul 2026) | No charge |
| Hargreaves Lansdown | £0 (old £25/line abolished September 2019) |
| interactive investor | £0 including in-specie |
| Vanguard UK | £0 |
| Trading 212 | £0 |
| Freetrade | £0 UK stock; US £17 per holding still published |
| Nutmeg | Usual route cash; agreed in-specie £20 per line |
| Moneybox | No published exit tariff found on this snapshot — not treated as £0 |
| Easy-access Cash ISA banks | No major transfer-out tariff found; fixed-term interest penalties possible |
Some links in this table are referral links. We may earn a commission if you use them, at no extra cost to you. Rankings are based on our review methodology, not commission.
Dealing and FX on a cash (sold) transfer are separate from exit fees. Hargreaves Lansdown’s old £25 per line is in the past. Freetrade’s US £17 per holding was still published on 30 August 2026.
FSCS and the three things called CASS
A Cash ISA is a deposit, covered up to £120,000 per person per authorised firm from 1 December 2025. A Stocks and Shares shortfall at an investment firm is still £85,000. There is no third in-transit FSCS pot.
Who holds the money at failure matters. See FSCS protection limits.
Three things called CASS: the Current Account Switch Service does not move ISAs. The Pay.UK Cash ISA Transfer Service is manager messaging for Cash ISA transfers.
FCA Client Assets Sourcebook is how firms hold client money. Only the ISA transfer process (and Cash ISA Transfer Service messaging) moves a Cash ISA.
Easy-access cash is a different product from a Cash ISA transfer: easy-access savings accounts in the UK.
The catch
Important things to know
- Start with the new provider. Do not withdraw and reopen.
- Cash-to-cash: 15 working days. Other types: 30 calendar days, not 30 working days.
- 2027 Cash ISA changes are not in force.
- Cash ISA deposits: FSCS £120,000.
- Lifetime ISA to Lifetime ISA does not trigger the 25% charge. Type-change usually does.
- The Current Account Switch Service does not move ISAs.
- Hargreaves Lansdown £25 per line is abolished. Freetrade US £17 per holding was still published on this snapshot.
- This page does not rank destinations.
How to transfer an ISA: FAQs
How do you transfer an ISA?
Start with the provider you want to move to. They send a transfer instruction to the old provider. Money and history move direct. It is not a Current Account Switch Service switch, not a withdrawal, and not a recommendation to transfer.
What is an ISA transfer?
An ISA transfer is a manager-to-manager move of the tax-free wrapper. Current-year amounts that are fully passed across are treated as made to the new manager. It is not a new DIY subscription. This is general information, not personal advice.
How long does a cash ISA transfer take?
Cash ISA to Cash ISA has a 15 working-day clock, from when the new manager receives the instruction. Industry aim is 85% in 7 working days. Notice or fixed-term waiting to avoid a penalty is a new instruction and a fresh clock.
How long does a stocks and shares ISA transfer take?
Other types, including Stocks and Shares, Lifetime ISA, and cross-type, have a 30 calendar-day clock, not 30 working days. Platform in-specie tables can run longer than that statutory maximum. Investments can fall as well as rise.
Can I transfer an ISA by withdrawing the money?
See Why a transfer is not a withdrawal above.
Does the Current Account Switch Service move an ISA?
No. The Current Account Switch Service FAQ says it cannot switch savings accounts or ISAs. The Pay.UK Cash ISA Transfer Service is a different rail for manager messaging. FCA Client Assets Sourcebook is a third CASS.
Can I transfer a Lifetime ISA without the 25% charge?
See Lifetime ISA special rules above.
Is a Cash ISA covered by FSCS during a transfer?
See FSCS and the three things called CASS above.
What is the difference between an in-specie transfer and a cash transfer?
In-specie moves the holdings. You usually stay invested but often cannot deal until it completes. A cash transfer sells first, so you are out of the market until rebuy. Capital can fall or you can miss a rise. Fractionals are often sold inside the wrapper.
Does transferring an ISA use this year’s allowance?
A transfer is not a new subscription in the usual sense. Current-year amounts fully passed across are treated as made to the new manager. That is not a reason to withdraw and reopen. Previous-year capital sits outside the shelter once withdrawn.
Get our weekly email
The Friday Finance Lowdown — five minutes of the money stuff worth knowing.
Free to join. See our privacy policy for how we handle your email address.
How we make money: some links on this page are referral links, and we may earn a commission if you use them, at no extra cost to you. Commission never affects which products we include or how we rate them. Read our full disclosure